Five Things Said About the CONFOTUR Law, and What the Text Supports
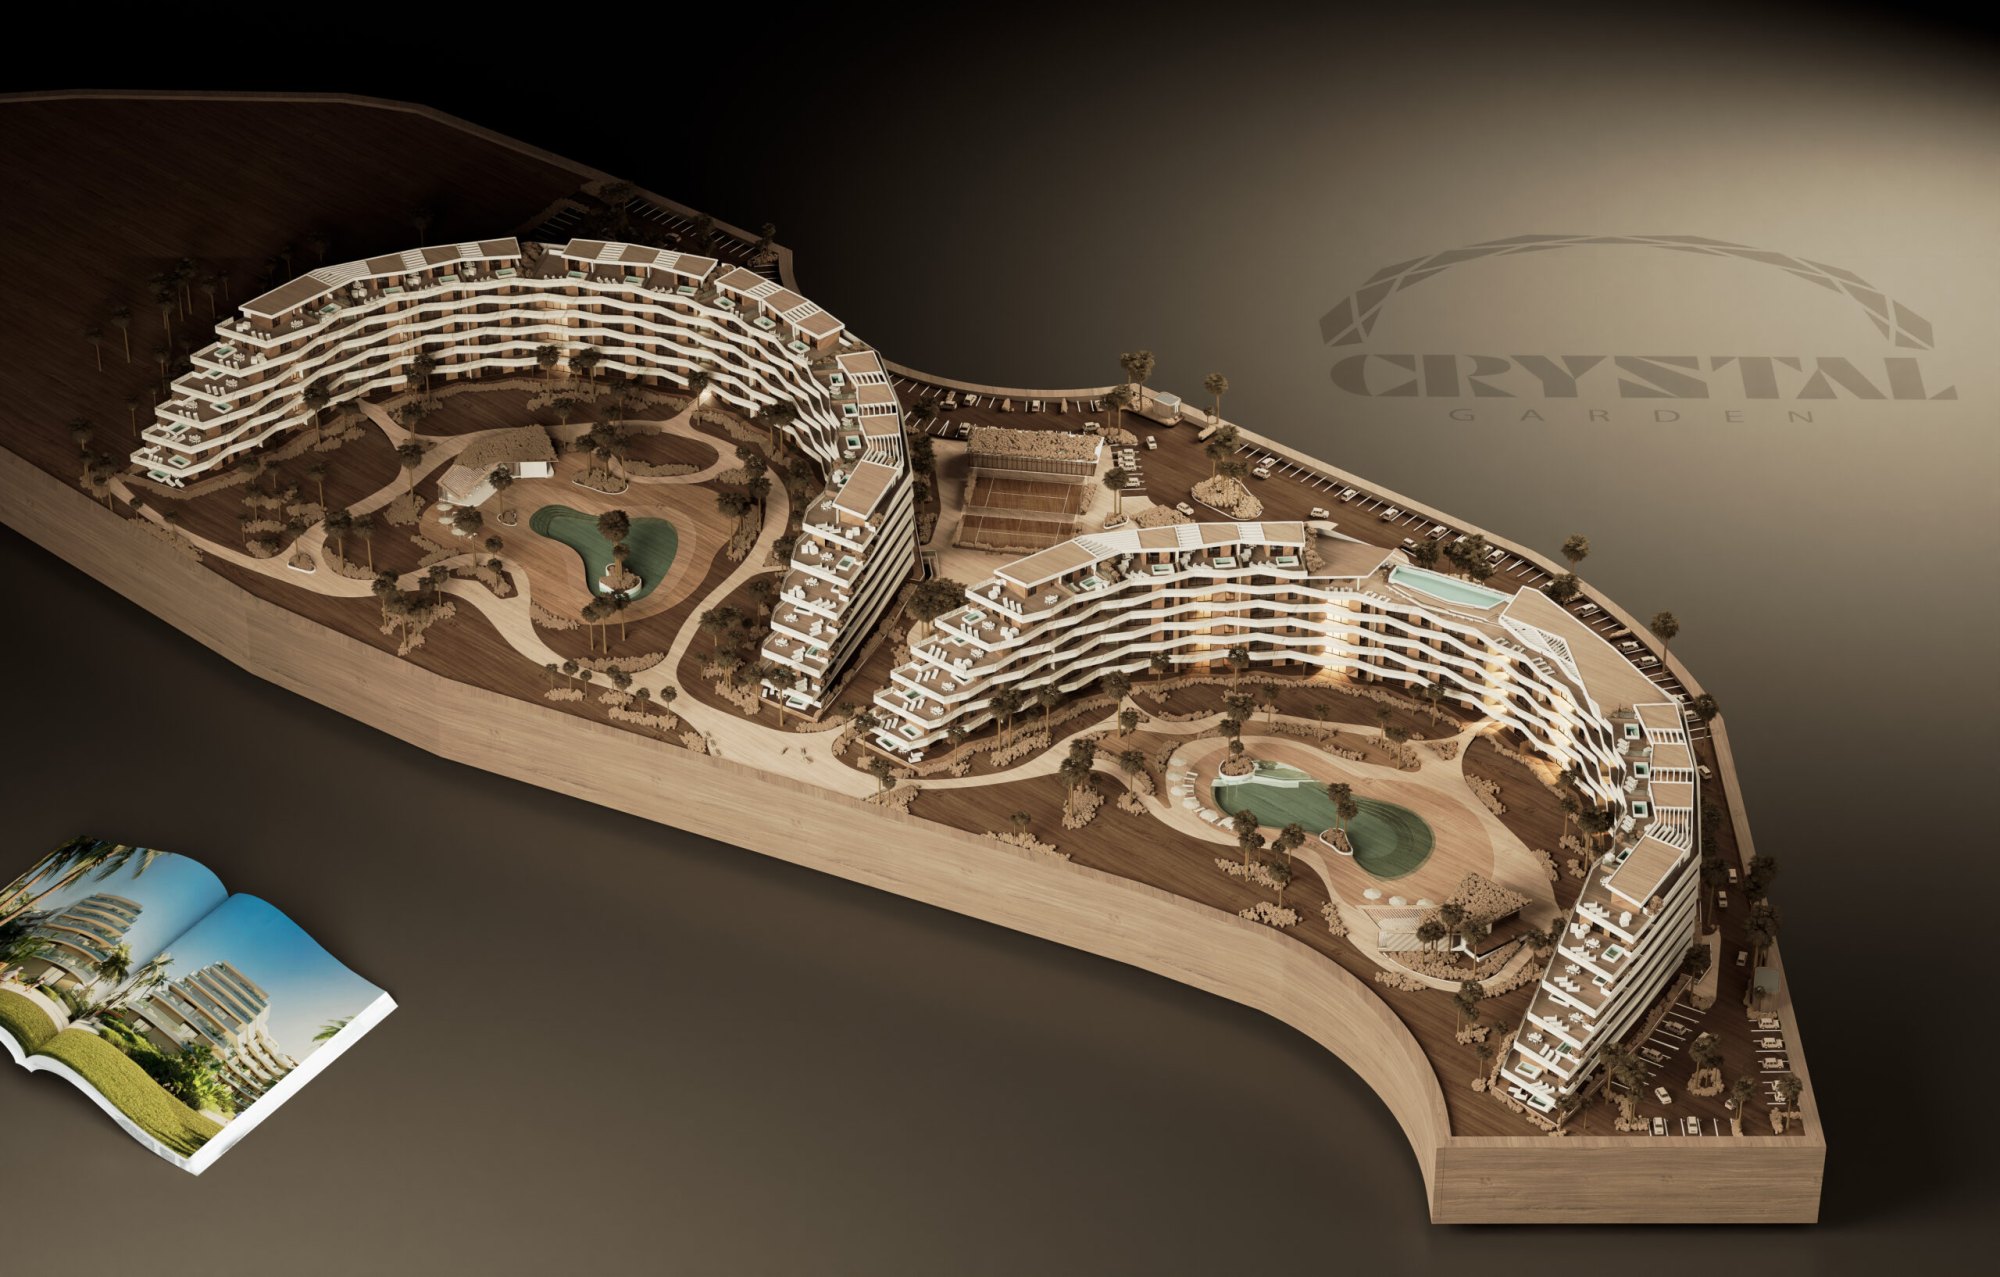
Almost everything written about CONFOTUR compresses Law 158-01 into a slogan, and slogans drift. This page takes five claims a buyer at Crystal Garden, a development of 196 residences in Cap Cana, is likely to hear, and sets each one beside what the law and the Dominican authorities actually publish. Where the answer depends on a particular unit or a particular buyer, it says so and names who can settle it, rather than filling the gap with a guess.
Claim one: “CONFOTUR is a special arrangement for this development”
It is a national law, not a feature of any single building. Law 158-01, the statute that promotes tourism development, was enacted in 2001 and amended in 2013 by Law 195-13. Its name is the acronym of the body it set up, the Consejo de Fomento Turístico, and that council is the only party that can make a project eligible: it approves a tourism project by resolution, first provisionally and then definitively. A developer can plan for classification, apply for it and describe it, but cannot award it to itself.
For a buyer the useful consequence is that the claim can be checked. The Ministry of Tourism's CONFOTUR portal runs a public consultation page where a project's classification can be looked up and filtered by stage, by status (approved, rejected or postponed) and by province. Crystal Garden's own page describes its residences as eligible for the exemption; reading the project's entry on that portal, on the day you are deciding, turns that statement into something you have seen for yourself.
Claim two: “Under CONFOTUR, the owner pays no tax”
The law's benefits page lists a long run of incentives, and most of them are not aimed at the person buying a home. An exclusion from income tax for those who undertake or invest in the regulated activity, relief from import duties and ITBIS on the equipment and furnishings a project brings in to be built and fitted out for the first time, fee relief for contractors on plans and construction, and no withholding on the project's financing: those are incentives for the tourism enterprise. Quoting them to a condo buyer overstates the law.
Two exemptions do reach a first buyer. One is the 3% tax on the transfer of real estate, spared on the purchase from the developer. The other is the 1% annual property tax, the IPI, which outside CONFOTUR falls only on the part of a property's value above a threshold adjusted every year, so what it is worth to a given owner depends on how the residence is assessed. Rent is governed by other rules, and no source we can cite extends either exemption to it. Two of those rules matter before you model a return: short-term tourist accommodation carries 18% ITBIS, which the host answers for rather than the platform taking the booking, and a non-resident owner faces a 27% withholding on gross rent, with no deductions allowed, which settles the tax on that income outright. Rates and how they are applied change, so confirm them for the year you file.
| Incentive in Law 158-01 | Who it is written for |
|---|---|
| 3% transfer tax exemption on the purchase | The first buyer from the developer |
| 1% annual property tax (IPI) exemption | A qualifying project and its first buyers |
| Exclusion from income tax | The developer and those investing in the project |
| Import duty and ITBIS relief on equipment and furnishings | The developer, to build and fit out |
| No withholding on the project's financing | The developer |
Claim three: “Buyers get fifteen tax-free years”
The fifteen years are real, but the text does not frame them the way the slogan does. Article 7 of the law sets a fifteen-year IPI exemption for qualifying projects and counts it from the completion of construction; it is addressed to the enterprises the law regulates. The tax authority's published answer on what first acquirers receive lists the transfer-tax and IPI exemptions without stating a term of its own.
Two practical points follow for a Crystal Garden buyer. First, the clock is tied to completion of construction; the site's own summary speaks of delivery, which is projected for 2027, but completion and handover need not fall on the same day, so treat 2027 as an indication rather than a start date. Second, how the period applies to a particular residence and a particular owner is not something this page, or any marketing page, can settle. It is a question for your attorney, who can point to the resolution and the title record that govern your unit.
Claim four: “The exemption stays with the apartment, whoever owns it”
Article 4 limits the buyer-side benefits to first buyers from the developer and excludes resales. So the exemption does not travel with the residence to whoever buys it from you. Crystal Garden's own summary words this carefully, saying the exemption carries through the years you hold the residence, and that is the right reading: the years you hold it, not the years anyone holds it.
Whoever later buys the residence from you therefore pays the 3% transfer tax on that purchase, and the property moves into the ordinary IPI rules, under which only value above the annual threshold is taxed. That is worth remembering when you compare a first purchase with a resale elsewhere in Cap Cana: part of the gap between them sits in tax, not in the price.
Claim five: “It is applied automatically at closing”
Nothing about CONFOTUR happens by itself. The exemption has to be filed for and recorded on the title, and the order of documents in an off-plan purchase explains why that takes time. A purchase of this kind usually begins with a promesa de venta, a contract that governs the transaction until the definitive sale contract is signed and that does not, on its own, transfer ownership. Under Ley 108-05, the Real Estate Registry Law, it is registration that creates and validates the right (Article 90), and the certificado de título is the State-guaranteed document that proves it (Article 91).
Put simply, the record that matters sits on a title you will hold only once the definitive sale is registered. Before signing, put three questions to your attorney: which resolution classifies the project, how and when the exemption will be filed, and how you will see it recorded once your title is issued.
Common questions
- Is CONFOTUR the law that lets foreigners buy property?
- No. Foreign ownership rests on separate rules: a foreigner may purchase Dominican property and hold the title personally, with the same rights as a Dominican citizen and no residency condition, and title is recorded under Ley 108-05. CONFOTUR, Law 158-01, is a tourism-investment law that adds two tax exemptions for first buyers in classified projects. A buyer can rely on the first without the second, which is why the two should never be read as one promise.
- Where can I check whether a project is classified?
- On the public consultation page of the Ministry of Tourism's CONFOTUR portal, which filters by provisional or definitive classification, by status and by province. Read the entry on the day you decide: a classification is a live record, not a fixed trait of a building.
- Does a definitive classification carry more weight than a provisional one?
- Yes. To grant the definitive stage, the council's published requirements include a valid environmental authorisation from the Ministry of Environment and a full study of the project's economic and financial feasibility, together with the reference of any provisional resolution. The provisional stage rests on preliminary documents. The ministry gives no validity period for either stage, so this page states none.
- Does CONFOTUR make a residence's rental income tax-free?
- No source we can cite says it does, and the prudent reading is to assume rent is taxed in full. CONFOTUR's buyer-side exemptions concern the transfer of the property and the yearly tax on holding it; rent is assessed under separate rules. For your own case, ask a Dominican tax professional.
Want the details for your own situation?
Ask about availability, layouts or the buying process, and someone from the sales team will get back to you.
Get in touch